No annual fee credit cards in the US: which one fits your spending?

If you want a card that costs nothing to hold, Woodo's top pick among no annual fee credit cards in the US right now is the Hilton Honors American Express Surpass® Card. It earns 12x points on stays booked directly with Hilton hotels and resorts, 3x on everything else, and hands back up to $200 in Hilton statement credits each year, all for a $0 annual fee. That mix of earn rate and recurring credit is why it leads. Every card below charges nothing yearly too, so the real question is which spending pattern each one rewards most. Here's the full shortlist.
| Card | Annual fee | What it earns or offers | Sign-up offer | Best for |
|---|---|---|---|---|
| Hilton Honors American Express Surpass® Card | $0 | 12x points on direct Hilton stays, plus up to $200 Hilton credit a year | None listed | Frequent Hilton guests |
| Hilton Honors American Express Card | $0 | 7x points on direct Hilton stays, no foreign transaction fees | None listed | Occasional Hilton stays and travel abroad |
| Chase United Explorer Card | $0 | Free first checked bag, 2x on dining and hotels, United miles | Up to 60,000 bonus miles after qualifying activities | United flyers |
| Delta SkyMiles® Gold American Express Card | $0 | $200 Delta flight credit after $10,000 spend, $100 Delta Stays credit | None listed | Regular Delta flyers |
| Delta SkyMiles® Blue American Express Card | $0 | Pay with Miles, no foreign transaction fees | None listed | Casual Delta flyers who travel abroad |
| Chase IHG One Rewards Credit Card | $0 | Up to 17x at IHG hotels, 3x on dining, gas and groceries | 125,000 bonus points after $2,000 spend in 3 months | IHG guests and everyday spenders |
The top no annual fee credit cards in the US, card by card
Hilton Honors American Express Surpass® Card
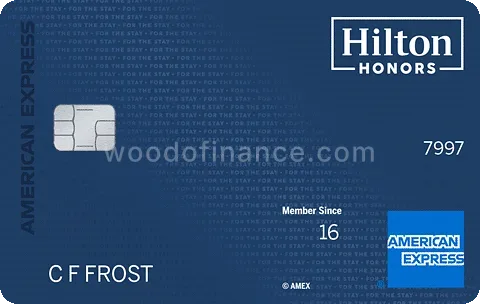
This card suits anyone who stays at Hilton properties more than a few times a year. The Hilton Honors American Express Surpass® Card earns 12x points on purchases made directly with hotels and resorts in the Hilton portfolio, 6x on US restaurants, US supermarkets and US gas stations, 4x on US online retail, and 3x on everything else. The standout is the $200 Hilton credit: up to $50 in statement credits each quarter on direct Hilton purchases. You also get complimentary Hilton Honors Gold Status, which includes the fifth night free on standard award stays of five nights or more and an 80% bonus on base points.
What it costs is simple: $0 a year, with a purchase rate of 19.74% to 28.74% variable APR. The catch is that the headline value comes from Hilton spending. If you rarely stay at Hilton, that $200 credit and the 12x rate do little for you, and the 3x base rate is where your everyday spending lands. Carry a balance and the APR erases rewards fast, so this one rewards paying in full.
Hilton Honors American Express Card
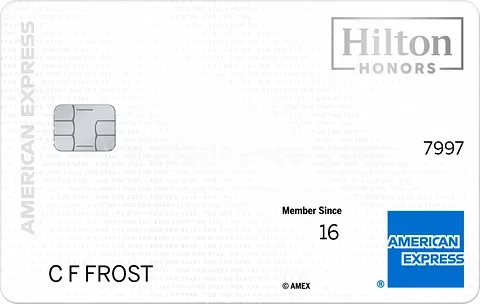
The Hilton Honors American Express Card is the lighter sibling. It earns 7x points on direct Hilton stays, 5x on US restaurants, US supermarkets and US gas stations, and 3x on everything else. You get Hilton Honors Silver Status with a 20% bonus on base points. For a no annual fee card, one perk stands out for travellers: no foreign transaction fees, so purchases abroad don't carry an extra charge from American Express.
It costs $0 a year at a 19.74% to 28.74% variable APR. The catch is the lower earn rate compared with the Surpass card, and no $200 recurring credit. If you stay at Hilton now and then and want a travel-friendly card for trips overseas, this fits. Heavy Hilton guests will out-earn the fee gap on the Surpass instead.
Chase United Explorer Card
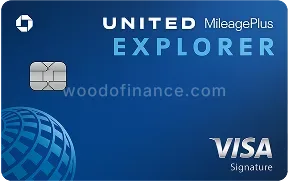
If you fly United, the Chase United Explorer Card earns its keep through airline perks rather than a flat rate. You get a free first checked bag, two United Club one-time passes a year, priority boarding, and over $500 in annual partner credits. On spending, it pays 2x miles on hotel stays booked with the hotel, 2x on dining including eligible delivery, and 1x on everything else. The sign-up offer, as recorded on 1 November 2026, is up to 60,000 bonus miles after qualifying activities: 50,000 after $3,000 of purchases in the first three months, plus 10,000 after adding an authorized user.
It costs $0 a year at 19.99% to 28.49% variable APR. The value depends heavily on flying United often enough to use the checked bag and lounge perks. If you don't, a flat-rate card may suit you better. Confirm the current sign-up offer on the card's page before you apply, since these terms change.
Delta SkyMiles® Gold American Express Card
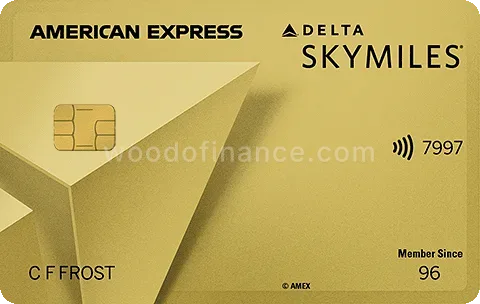
The Delta SkyMiles® Gold American Express Card works for regular Delta flyers who want travel credits without a yearly fee. It gives a $200 Delta flight credit after you spend $10,000 in a calendar year, up to $100 in annual Delta Stays credits for prepaid hotels and vacation rentals booked through Delta, and 20% back as a statement credit on eligible in-flight food and beverage purchases. Base earning is 1x miles on other eligible purchases.
The annual fee is $0, with a 19.74% to 28.74% variable APR. The catch is that the $200 flight credit needs $10,000 of spending to unlock, so light spenders may never reach it. This card pays off when Delta is your main airline and you put enough through the card each year.
How to choose a no annual fee card in the US
Start with the "Best for" column, then read "What it earns or offers". Every card here charges $0 a year, so the comparison is about which rewards match your real spending, not about recovering a fee. The fastest filter is loyalty. Four of these six cards are tied to a specific hotel group or airline. That makes them powerful if you already stay at Hilton or IHG, or fly United or Delta, and much weaker if you don't.
Next, weigh the trade-offs that matter for everyday use. If you spend across many categories, a card with a strong base rate like the Surpass card's 3x, or the IHG card's 2x and 3x on dining, gas and groceries, beats a 1x airline card for general purchases. If you travel overseas, look for the no foreign transaction fees note, which the Hilton Honors American Express Card and the Delta SkyMiles Blue card both carry. And check the purchase APR. Every card here sits in a similar range, so the rate only bites if you carry a balance, which wipes out rewards no matter how high the earn rate. The cleanest way to see which categories dominate your spending is to look at your own statements rather than guess.
How we picked these cards for the US
Woodo lists 95 no annual fee cards for the US market. This shortlist is drawn from that set and ordered by estimated yearly rewards on a typical spending mix, minus the annual fee; cards that publish no reward rates follow, cheapest annual fee first. All figures here were recorded on 1 November 2026. No issuer pays Woodo for placement, and no issuer can move a card up the list. You can see the full set and filter it yourself on Woodo's no annual fee credit cards comparison.
Your next step
Pick the card whose "Best for" line matches how you actually spend, then open its page to confirm the current sign-up offer and APR before applying. If you're not sure which loyalty programme or category dominates your spending, the honest answer is in your past statements. Uploading a few months to Woodo's statement converter shows which categories take the biggest share, and that is what decides the right card. When you're ready to compare side by side, browse the full list on Woodo's credit card comparison.
FAQ
Do no annual fee credit cards really cost nothing?
Yes, every card in this shortlist carries a $0 annual fee, so holding the card costs nothing each year. The costs that remain are interest and transaction fees. If you carry a balance, the purchase APR applies, and these cards range from 19.49% to 28.74% variable depending on the card. Some charge foreign transaction fees unless the card states otherwise. The Hilton Honors American Express Card and the Delta SkyMiles Blue American Express Card both advertise no foreign transaction fees. The simplest way to keep a no annual fee card genuinely free is to pay the statement balance in full each month and avoid interest entirely.
What income or credit do I need to qualify?
Issuers set their own eligibility rules, and no card guarantees approval. The card data here does not list specific income thresholds for these US cards, so check each card's page for current requirements before applying. In general, rewards cards from American Express and Chase expect a solid credit history. Applying for several cards in a short window can hurt your odds, so space out applications. Reviewing your own statements first helps you confirm you can clear the balance each month, which matters more than any single approval number. Apply for the card whose rewards match your spending rather than the one with the flashiest offer.
How are the rewards paid out?
It depends on the card's programme. The Hilton cards earn Hilton Honors points, the Chase IHG card earns IHG One Rewards points, and the Delta and United cards earn airline miles. Those points and miles are redeemed inside each loyalty programme, mainly for stays or flights. Some perks arrive as statement credits instead. The Delta SkyMiles Gold card gives a $200 Delta flight credit after $10,000 of spending and up to $100 in Delta Stays credits, and the Hilton Surpass card returns up to $200 in Hilton statement credits a year. Read each card's page to see exactly how its rewards land.
When do the sign-up bonuses need to be earned?
Each offer has a spending window and a deadline, so read the terms before you count on the bonus. As recorded on 1 November 2026, the Chase United Explorer Card offers up to 60,000 bonus miles, with 50,000 after $3,000 of purchases in the first three months and 10,000 after adding an authorized user. The Chase IHG One Rewards Credit Card offers 125,000 bonus points after spending $2,000 in the first three months. Offers change often, so confirm the current terms on the card's page before applying. The other cards in this shortlist have no sign-up offer listed.
Which of these cards is best for spending abroad?
For overseas purchases, look for a card that states no foreign transaction fees. In this shortlist, the Hilton Honors American Express Card and the Delta SkyMiles Blue American Express Card both advertise no foreign transaction fees from American Express. That means purchases made abroad don't carry an extra percentage charge on top of the exchange. The other cards here may apply a foreign transaction fee, so check each card's page if you travel internationally. If trips abroad are a regular part of your spending, a card with no foreign transaction fees usually beats a higher earn rate that gets eaten by surcharges overseas.
Is a hotel or airline card worth it if I'm not loyal to one brand?
Probably not for the branded perks, though some still earn well on everyday spending. Four of these six cards tie their biggest value to Hilton, IHG, United or Delta. If you don't stay or fly with those brands, perks like free checked bags, elite status and hotel credits go unused. Look instead at the base earn rate. The Hilton Surpass card pays 3x on everything else, and the Chase IHG One Rewards Credit Card pays 2x on all other purchases plus 3x on dining, gas and groceries. Those rates work across general spending, which makes them friendlier to someone without strong brand loyalty.
What should I check before I apply?
Check four things: the annual fee, the earn rate on your biggest spending categories, any foreign transaction fee, and the current sign-up offer. Every card here has a $0 annual fee, so focus on whether its rewards match where your money actually goes. Confirm the purchase APR too, since carrying a balance cancels out rewards on any card. Offers and rates change, so the figures in this guide were recorded on 1 November 2026 and should be verified on the card's own page. Looking at a few months of your real statements tells you which categories dominate, and that is the clearest signal of which card fits.
Rates and fees
Rates and fees as published by each issuer and recorded by Woodo on 1 November 2026. Check the issuer's terms for the current figures before you apply. Woodo is not paid by any card issuer and earns no commission on these links. We are not affiliated with any issuer.
- Hilton Honors American Express Surpass® Card. Annual membership fee: $0. Purchase APR: 19.74% - 28.74% variable APR, based on creditworthiness and the Prime Rate.
- Hilton Honors American Express Card. Annual membership fee: $0. Purchase APR: 19.74% - 28.74% variable APR, based on creditworthiness and the Prime Rate.
- United Explorer Card. Annual membership fee: $0. Purchase APR: 19.99% - 28.49% variable APR, based on creditworthiness and the Prime Rate.
- Delta SkyMiles® Gold American Express Card. Annual membership fee: $0. Purchase APR: 19.74% - 28.74% variable APR, based on creditworthiness and the Prime Rate.
- Delta SkyMiles® Blue American Express Card. Annual membership fee: $0. Purchase APR: 19.74% - 28.74% variable APR, based on creditworthiness and the Prime Rate.
- IHG One Rewards Credit Card. Annual membership fee: $0. Purchase APR: 19.49% - 27.99% variable APR, based on creditworthiness and the Prime Rate.
Stop logging every coffee.Do it on a Sunday.
One PDF, once a month. Woodo's AI pulls every transaction, sorts by category, and shows you where the money went — finished before your coffee cools.
More from Woodo Blog
Which German card hands you the biggest sign-up bonus?
The easybank Kreditkarte is Woodo's top sign-up bonus pick in Germany, with a €50 start bonus and no annual fee. Here's how it compares with five other cards and which bonus suits how you spend.
Which cashback card in Sweden puts the most back in your pocket?
Woodo's top cashback pick in Sweden is the American Express Blue Cashback, which pays 1.25% back on everything you buy. Here's how six cards compare, and which one fits how you actually spend.
Which no annual fee credit card in Canada is worth carrying?
Woodo ranks the More Rewards RBC Visa Infinite first among no annual fee credit cards in Canada, for its 4x points on everything at a $0 fee. Here's how six cards compare on rewards, rates and perks.