Which cashback card in Switzerland actually pays you back?

If you want a simple answer, Woodo's top pick among cashback credit cards in Switzerland is the poinz Cards from Swisscard. It pays 1% cashback with the poinz American Express on everything you buy, charges no annual fee, and drops the cash into your poinz account within 24 hours so you can move it to your bank. That mix of a flat reward rate and zero holding cost is what puts it first. The rest of this guide shows how the other five cards compare, and which one fits the way you actually spend.
| Card | Annual fee | What it earns | Sign-up offer | Best for |
|---|---|---|---|---|
| Swisscard poinz Cards | No annual fee | 1% cashback with the Amex, 0.25% with the Visa | 3% cashback on the Amex for the first three months, up to CHF 100 | Flat cashback with no fee |
| Swisscard Cashback Cards | No annual fee | 1% cashback with the Amex, 0.25% with the Mastercard or Visa | 5% cashback on the Amex for the first three months, up to CHF 100 | A bigger opening bonus |
| Bonus Card LOEB Club Visa Card | No annual fee | 2% at LOEB, 0.50% everywhere else | None listed | Regular LOEB shoppers |
| Cembra TCS Travel Mastercard Gold | CHF 100 a year | 1% turnover bonus on all spending | None listed | Drivers and travellers |
| Bonus Card PKZ Insider Card Visa | No annual fee | 1% at PKZ, 0.50% everywhere else | None listed | PKZ loyalty shoppers |
| Cembra Certo! Mastercard World | No annual fee | 1% at Migros, Coop and SBB, 0.25% elsewhere | None listed | Grocery and rail spenders |
The top cashback cards in Switzerland, card by card
Swisscard poinz Cards
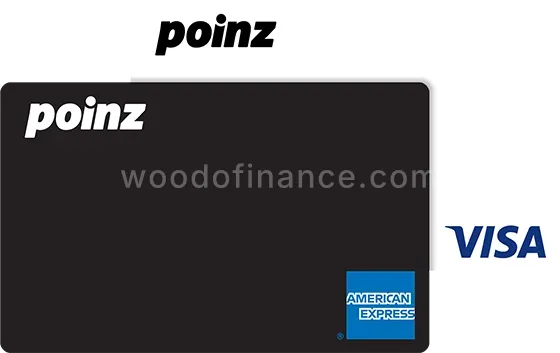
The poinz Cards suit anyone who wants cashback without thinking about categories or fees. You get a duo: the poinz American Express and the poinz Visa, both free. The Amex pays 1% cashback on everything, the Visa pays 0.25%, and the money lands in your poinz account within 24 hours. From there you can move it to a bank account. That fast payout sets it apart from cards that credit once a year.
There's no annual fee, so every franc of cashback stays with you. The opening offer gives 3% cashback on the American Express card for the first three months, up to CHF 100. The card also carries Return Protection Insurance. The one catch: the strong rate sits on the Amex, which fewer Swiss merchants accept than Visa, so you'll lean on the lower-earning Visa for some purchases. Check the current offer on the card's page before you apply, since opening deals change.
Swisscard Cashback Cards
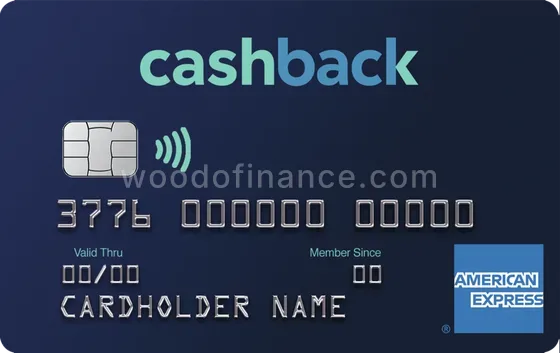
The Cashback Cards work much like the poinz pair. You get an American Express plus a Mastercard or Visa for one annual fee, and that fee is nothing. The Amex pays 1% cashback, the second card 0.25%, and additional cards cost nothing extra. The difference from the poinz duo is the payout timing: cashback here is credited once a year rather than within a day.
What might tip you toward this one is the opening offer. It gives 5% cashback on the American Express card for the first three months, up to CHF 100, two points higher than the poinz version over the same window. The purchase rate is 12% p.a. and the foreign transaction fee is 2.5%, so it's not a card to lean on abroad. If you clear the balance each month and want the bigger starter bonus, it's a close second. Confirm the live offer before applying.
Bonus Card LOEB Club Visa Card
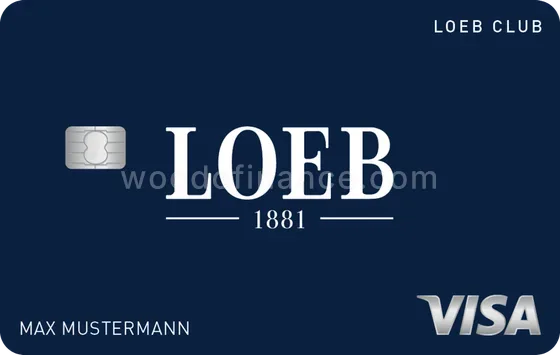
The LOEB Club Visa Card from Bonus Card earns its place if you shop at LOEB. You collect 2 LOEB Goldpunkte per franc spent there, worth 2% off through vouchers sent four times a year, and a 0.50% turnover bonus on spending elsewhere, paid once a year as a gift card from CHF 10. It doubles as LOEB Club membership, and spending CHF 2,400 over 24 months lifts you to LOEB Gold Club status: 4% at LOEB and 1% everywhere else.
There's no annual fee, and the additional card is free too. You also get a best price guarantee, a 24-month warranty extension on purchases paid at least half with the card, shopping legal protection and delivery insurance. The catch is obvious from the rates: the everyday 0.50% is modest, so this card rewards you in proportion to how much of your spending goes to LOEB. The purchase rate is 12% p.a. and the foreign transaction fee is 2%.
Cembra TCS Travel Mastercard Gold
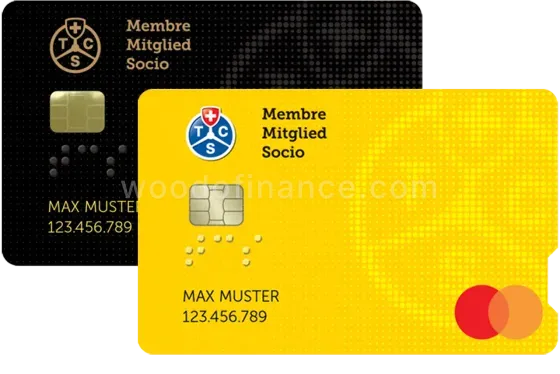
The TCS Travel Mastercard Gold from Cembra is the one card here with an annual fee, CHF 100 a year, and the one built with drivers and travellers in mind. It pays a 1% turnover bonus on all card spending, charges no fee for cash withdrawals abroad, and carries the lowest foreign transaction fee in this group at 1.5%. You can save up to 5 Rp./L at more than 900 fuel stations and get a 5% discount at 382,000+ charging points through TCS eCharge.
The trade-off is the fee. A flat 1% matches the free Swisscard cards, so the CHF 100 only makes sense if you use the fuel savings, the charging discount or the cheaper foreign spending enough to cover it. If you drive often or spend abroad regularly, the maths can work. If you don't, a no-fee 1% card leaves you better off. The purchase rate is 12% p.a.
How to choose a cashback card in Switzerland
Start with the "What it earns" column, then read the annual fee next to it. For most people, a flat 1% with no fee beats a higher headline rate that only applies at one shop. Several cards here top out at 1% on everyday spending, so the real question is where your money goes. If a big slice lands at LOEB, PKZ, Migros, Coop or SBB, a store-linked card can pay more than a flat one. If your spending is spread around, a flat rate wins.
Watch two other things. First, network: the strongest rates on the Swisscard duos sit on the American Express, which fewer Swiss shops take than Visa or Mastercard, so you'll fall back to the lower rate at times. Second, foreign transaction fees, which range from 1.5% to 2.5% here and quietly eat into any cashback when you travel. Payout timing matters too: the poinz account credits within 24 hours, while most of the others pay once a year. Only pick the one card with a fee, the TCS Travel Mastercard Gold, if its fuel and charging perks clearly cover the CHF 100.
The cleanest way to see which card fits is to look at your own spending by category. Pulling a few months of statements into a spreadsheet built from your statement PDFs shows exactly how much runs through groceries, rail, fuel and general shopping, which is the number that decides between a store card and a flat one.
How we picked these cards
This shortlist comes from the 22 cards Woodo lists in the cashback category for Switzerland. The figures were recorded on 2 October 2026, and you can see the full set on Woodo's cashback card comparison for Switzerland. We ranked them by estimated yearly rewards on a typical spending mix, minus the annual fee; cards that publish no reward rates follow, cheapest annual fee first. No issuer pays Woodo for placement, and no issuer can pay to move a card up the list. We check the issuer pages every month, but offers and rates change, so confirm the details on each card's page before you apply.
Your next step
Pick the card whose top earning categories match where your money actually goes, then open its page and confirm the current offer and fees before you apply. If you're still weighing options, the full Switzerland card comparison lets you sort by annual fee and reward rate. Uploading a few months of statements to Woodo shows which spending categories dominate your budget, and that breakdown is usually what decides whether a flat 1% card or a store-linked one puts more cashback in your pocket.
FAQ
Do cashback credit cards in Switzerland charge an annual fee?
Most of the cards on this shortlist charge no annual fee. The Swisscard poinz Cards, the Swisscard Cashback Cards, the LOEB Club Visa Card, the PKZ Insider Card Visa and the Certo! Mastercard World are all listed with no annual fee. The only exception here is the Cembra TCS Travel Mastercard Gold at CHF 100 a year. A no-fee card means every franc of cashback stays with you, which is why a flat 1% at zero cost often beats a card that charges a fee for a similar rate. Always confirm the fee on the card's own page, since terms change.
How is cashback paid out on these cards?
It depends on the card. The poinz Cards credit cashback to your poinz account within 24 hours, and you can move it to a bank account from there. The Swisscard Cashback Cards credit once a year. The LOEB Club Visa Card sends vouchers four times a year plus a yearly gift card from CHF 10, and the PKZ Insider Card Visa pays a turnover bonus once a year from CHF 10. If fast access to your cashback matters, the poinz account's 24-hour payout is the standout among these cards.
Which cashback card is best if I shop mostly at one store?
If most of your spending goes to a single retailer, a store-linked card can pay more than a flat one. The LOEB Club Visa Card earns 2% at LOEB, rising to 4% at LOEB Gold Club status after CHF 2,400 spent over 24 months. The PKZ Insider Card Visa earns 1% at PKZ, with higher rates on its Silver and Gold tiers. The Certo! Mastercard World pays 1% at Migros, Coop and SBB. For spending spread across many shops, a flat 1% card such as the poinz Cards usually wins.
What fees apply when I spend abroad?
Each card charges a foreign transaction fee on purchases in another currency. Among these cards, the Cembra TCS Travel Mastercard Gold is the cheapest at 1.5% and also waives the fee for cash withdrawals abroad. The LOEB Club Visa Card and the PKZ Insider Card Visa charge 2%, and the Swisscard Cashback Cards charge 2.5%. These fees can cancel out your cashback on foreign spending, so if you travel often, weigh the foreign transaction fee as heavily as the reward rate.
Does the American Express network limit where I can use these cards?
Yes, to a degree. The poinz Cards and the Swisscard Cashback Cards put their top 1% rate on an American Express card, which fewer Swiss merchants accept than Visa or Mastercard. That's why both come as a duo: a second card on Visa or Mastercard covers the shops that don't take Amex, though that card earns the lower 0.25% rate. In practice you'll earn 1% at Amex-friendly places and 0.25% elsewhere, so your real cashback depends on where you shop.
Is there a sign-up offer on these cards?
Two of the six list a sign-up offer. The Swisscard Cashback Cards give 5% cashback on the American Express card for the first three months, up to CHF 100. The poinz Cards give 3% cashback on the Amex over the same first three months, also up to CHF 100. The other cards have no offer listed as of 2 October 2026. Sign-up offers change often, so check the current deal on the card's page before you apply, and note that both offers run only for the opening three-month window.
Which cashback card suits a driver in Switzerland?
The Cembra TCS Travel Mastercard Gold is built with drivers in mind. It saves up to 5 Rp./L at more than 900 fuel stations, gives a 5% discount at 382,000+ charging points through TCS eCharge, and pays a 1% turnover bonus on all spending. It carries a CHF 100 annual fee, so it only pays off if your fuel savings, charging discount and cheaper foreign spending outweigh that cost. If you drive rarely, a no-fee 1% card leaves you better off overall.
What should I check before applying for a cashback card?
Check four things: the annual fee, the reward rate on your biggest spending categories, the foreign transaction fee, and how and when the cashback is paid. Match those against where your money actually goes each month. A card with a high rate at one store does nothing for you if you rarely shop there. Reviewing a few months of your own categorised spending before you apply is the surest way to see whether a flat-rate card or a store-linked one will pay you more.
Stop logging every coffee.Do it on a Sunday.
One PDF, once a month. Woodo's AI pulls every transaction, sorts by category, and shows you where the money went — finished before your coffee cools.
More from Woodo Blog
Which cashback credit card in Hong Kong actually pays you back?
Woodo's top cashback pick in Hong Kong is the Mox Credit Card, which pays 3% on groceries with no annual fee. Here's how it stacks up against five other cards and which one fits your spending.
Which US travel credit card earns the most on your spending?
Woodo's top travel pick is the Chase Freedom Unlimited, which earns 5% back on travel booked through Chase Travel and charges no annual fee. Here's how it stacks up against five other US cards and which one fits your trips.
Which cashback credit card in Singapore actually pays you back?
Woodo ranks the CIMB Visa Signature as the top cashback card in Singapore, with up to 10% on online shopping and groceries and no annual fee. Here's how it compares with five other cards, and which one fits your spending.