Which cashback credit card in the UK actually pays you?

If you want a quick answer, Woodo's top pick among cashback credit cards in the UK is the Santander UK Rewards Credit Card. It leads because it pays 3% on petrol, everyday travel and eating out in your first year, which beats the flat rates most rivals offer, and it carries no monthly account fee. That first-year rate drops to 0.25% afterwards, so it suits different people at different times. Below you'll find every card on Woodo's shortlist, what each one earns, and how to match a card to the way you actually spend.
| Card | Annual fee | What it earns | Sign-up offer | Best for |
|---|---|---|---|---|
| Santander UK Rewards Credit Card | No monthly account fee | 3% on fuel, transport and dining in year one, 0.25% after; 0.25% on everything else | New to Santander? Up to £40 in Uber vouchers | Drivers and commuters who eat out |
| Amazon Barclaycard rewards credit card | No monthly fee | 1% back on Amazon, 0.5% everywhere else | £20 Amazon Gift Card on approval, plus £10 after activation | Regular Amazon shoppers |
| Santander UK All in One Credit Card | £3 monthly account fee | 0.5% cashback (up to £10 a month) on all purchases | None listed | People who also want a 0% balance transfer |
| Co-operative Bank members cashback credit card | No annual fee | 0.5% at Co-op food stores, 0.3% everywhere else | None listed | Co-op Members and current account holders |
| Virgin Money Everyday Cashback Credit Card | No annual fee | 1% for the first 90 days, 0.25% after | 1% cashback on spending for the first 90 days | A short burst of higher cashback |
| Barclaycard Rewards | No annual fee | 0.25% back on eligible purchases | None listed | Fee-free spending abroad |
The top cashback cards in the UK, card by card
Santander UK Rewards Credit Card
This is the pick for anyone who spends a chunk of their month on fuel, trains, buses, taxis and eating out. In your first year the Santander UK Rewards Credit Card pays 3% on petrol, diesel and EV charging, 3% on everyday travel including TfL, and 3% on restaurants, cafes and takeaways. Everything else earns 0.25%.
It costs nothing in monthly account fees, and there are no foreign exchange fees on purchases abroad, which is handy on holiday. The purchase rate is 24.9% p.a. (variable), so clear the balance in full to keep the cashback worth having. The catch is simple: after year one those 3% categories drop to 0.25%, so the standout value sits in the first twelve months. New Santander customers can currently get up to £40 in Uber vouchers; confirm the live offer on the card's page before you apply.
Amazon Barclaycard rewards credit card
If a steady slice of your spending lands at Amazon, the Amazon Barclaycard rewards credit card earns 1% back in rewards there and 0.5% everywhere else. Amazon Prime members get 2% back during eligible events like Prime Day. There's no monthly fee, and new cardholders get 0% interest on purchases for 6 months from account opening.
The sign-up offer is a £20 Amazon Gift Card on approval, plus an extra £10 Gift Card once you activate in the Barclays or Barclaycard app. That app matters: this is an app-first account, so you manage it mostly from your phone. The purchase rate after the intro period is 28.9% p.a. (variable), among the higher rates here, so the 0% window is best treated as breathing room rather than a reason to carry a balance long term.
Santander UK All in One Credit Card
The Santander UK All in One Credit Card pays a flat 0.5% cashback on all purchases, capped at £10 a month. On top of that it runs 0% on purchases for 15 months and 0% on balance transfers for 15 months, with no balance transfer fee. That combination suits someone shifting an existing balance while still earning a little back on day-to-day spending.
The trade-off is a £3 monthly account fee, the only card here that charges one. At 0.5% cashback capped at £10, you'd need to spend fairly heavily each month before the cashback covers that fee, so the real value is in the long 0% periods rather than the rewards alone. The purchase rate afterwards is 23.9% p.a. (variable).
Co-operative Bank members cashback credit card
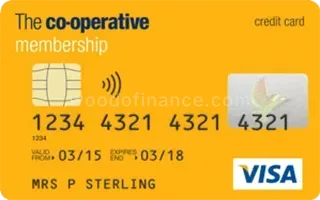
The Co-operative Bank members cashback credit card pays 0.5% cashback in Co-op food stores and 0.3% everywhere the Visa symbol shows (balance transfers and cash withdrawals excluded). There's no annual fee, no balance transfer fee, and the purchase rate of 18.2% p.a. (variable) is the lowest on this list.
The eligibility rules are stricter than the rest. You need to have held a Co-operative Bank or smile current account for at least 7 months (Cashminder accounts don't count), and you must be a Co-op Member with a membership number starting 633174. There's a 2.75% foreign transaction fee, so it's a weaker choice for travel. If you already bank with the Co-op and shop at Co-op stores, the low rate and fee-free structure make it worth a look.
How to choose a cashback credit card in the UK
Start with the "what it earns" column, then check it against where your money actually goes. A headline rate only pays if it lands on categories you use. The Santander Rewards card's 3% is excellent for drivers and commuters in year one, but useless if most of your spending is groceries. The Amazon card rewards one retailer. The Co-op card rewards one supermarket. Flat-rate options like the All in One or Barclaycard Rewards treat every purchase the same.
Read the annual fee next. Only the All in One charges one, at £3 a month, and its cashback is capped at £10 a month, so you have to spend enough to clear that fee before the rewards are real money. Then weigh the extras. If you spend abroad, the Santander Rewards and Barclaycard Rewards cards charge no foreign transaction fee, while the Co-op card charges 2.75%. If you're moving a balance, the All in One's 15 months at 0% with no transfer fee stands out.
One honest reminder: cashback only works if you clear the balance each month. Purchase rates here run from 18.2% to 28.9% p.a. (variable), and interest at those levels wipes out any rewards fast. The right card is the one whose top category matches your biggest spending line.
How we picked these cards
This shortlist comes from the 15 cards Woodo lists in the cashback category for the United Kingdom. The figures were recorded on 12 September 2026, and you can see the full set on Woodo's UK cashback card comparison. The order follows estimated yearly rewards on a typical spending mix, minus the annual fee; cards that publish no reward rates follow, cheapest annual fee first.
No issuer pays to appear here and none can pay to move up the list. Woodo rebuilds the comparison from issuer pages and checks it every month. Card terms change, so treat every figure as a snapshot from the as-of date and confirm the current details on each card's page before applying.
Your next step with cashback cards in the UK
Pick the one card whose best-earning category matches your largest monthly outgoing, then open its page and confirm the current rate and offer. If you're still unsure which category dominates, that's a question your statements answer. Uploading a few months of statements to Woodo shows which spending categories actually run your month, which is what decides the right card. When you're ready to compare side by side, Woodo's UK credit card comparison lets you filter by fee, reward rate and issuer.
FAQ
Do any of these cashback cards charge an annual fee?
Only one does. The Santander UK All in One Credit Card charges a £3 monthly account fee. Every other card on this list, the Santander Rewards card, both Barclaycard options, the Co-operative Bank card and the Virgin Money card, has no annual or monthly fee. With the All in One, its cashback is capped at £10 a month, so you'd need meaningful monthly spending before the rewards cover that £3 fee. The reason to accept the fee is usually the 15 months of 0% on purchases and balance transfers rather than the cashback itself. For pure fee-free cashback, the other cards are simpler.
How is the cashback paid and when do the rates change?
Cashback is earned as a percentage of what you spend in each category. Two cards have rates that step down over time. The Santander Rewards card pays 3% on fuel, travel and dining in your first year, then 0.25% after that. The Virgin Money Everyday Cashback Credit Card pays 1% for the first 90 days from account opening, then 0.25%. The Amazon Barclaycard pays in Amazon rewards rather than cash. The Co-op and Barclaycard Rewards cards keep steady rates. Check each card's page for exactly how and when rewards land, since this varies by issuer.
Which card is best for someone who spends abroad?
For fee-free spending abroad, the Santander UK Rewards Credit Card and Barclaycard Rewards both charge no foreign transaction fee. Barclaycard Rewards also lets you withdraw cash from an ATM abroad without charges and uses Visa's exchange rate. Avoid the Co-operative Bank card for travel, as it charges a 2.75% foreign transaction fee on overseas spending. If holidays and trips make up a real share of your spending, the fee-free cards keep more of your money and still earn a small amount of cashback on those purchases.
Are there eligibility requirements I should know about?
The Co-operative Bank members cashback credit card has the strictest rules. You must have held a Co-operative Bank or smile current account for at least 7 months, Cashminder accounts don't qualify, and you need to be a Co-op Member with a membership number starting 633174. The Amazon Barclaycard is app-first, so you'll need the Barclays or Barclaycard app to activate and manage it, and you must be 18 or over. The other cards follow standard credit card eligibility. No card can promise approval, since that depends on your own circumstances and the issuer's checks.
How long do the sign-up offers last?
Sign-up offers change often, so treat the ones listed here as a snapshot from 12 September 2026 and confirm the live offer before applying. New Santander customers can currently get up to £40 in Uber vouchers with the Rewards card. The Amazon Barclaycard offers a £20 Amazon Gift Card on approval plus £10 after you activate in the app. The Virgin Money card's offer is its first 90 days at 1% cashback. The All in One and Barclaycard Rewards have none listed. Each card's page shows the current terms and any deadlines.
Is a cashback card worth it if I sometimes carry a balance?
Generally no. Cashback on these cards runs from 0.25% to 3%, while purchase rates run from 18.2% to 28.9% p.a. (variable). Interest at those rates costs far more than the cashback you earn, so carrying a balance cancels the benefit. If you clear the balance in full each month, the Santander cards give you up to 56 days interest-free on purchases. If you expect to carry a balance, the All in One's 0% on purchases for 15 months buys time, but it's a repayment tool rather than a rewards play during that period.
Which card suits an everyday spender who doesn't fit a niche?
If your spending is spread evenly and doesn't cluster at Amazon, the Co-op or petrol stations, a flat-rate card is simplest. The Santander Rewards card still wins in year one because its 3% categories cover common everyday costs like fuel, transport and eating out. After that first year, a flat 0.5% card such as the Santander All in One or 0.3% from the Co-op card may suit steady, mixed spending better. The honest way to decide is to look at where your money actually went over the past few months, then pick the card whose top rate lands on your biggest category.
Stop logging every coffee.Do it on a Sunday.
One PDF, once a month. Woodo's AI pulls every transaction, sorts by category, and shows you where the money went — finished before your coffee cools.
More from Woodo Blog
Which cash back card actually pays you back in Canada?
Woodo's top cash back pick in Canada is the Desjardins Cash Back World Elite Mastercard, which earns up to 4% on every purchase. Here's how it stacks up against the rest of the shortlist, including two no-fee options.
Which US cash back credit card actually pays you most?
Woodo's top cash back pick is the Wells Fargo Active Cash Card, which pays a flat 2% on every purchase with no annual fee. Here's how it compares to five other US cards and which one fits your spending.
The cashback cards Atlanta digital nomads actually carry in 2026
Working remotely from Atlanta means your credit card needs to keep up whether you're at a Ponce City Market coffee shop or a café in Lisbon. We've compared the top cashback cards for digital nomads in 2026, focusing on no foreign transaction fees, versatile reward categories, and zero annual fees. Here's what's actually worth carrying.